Your Car Lease is Ending. Now What?
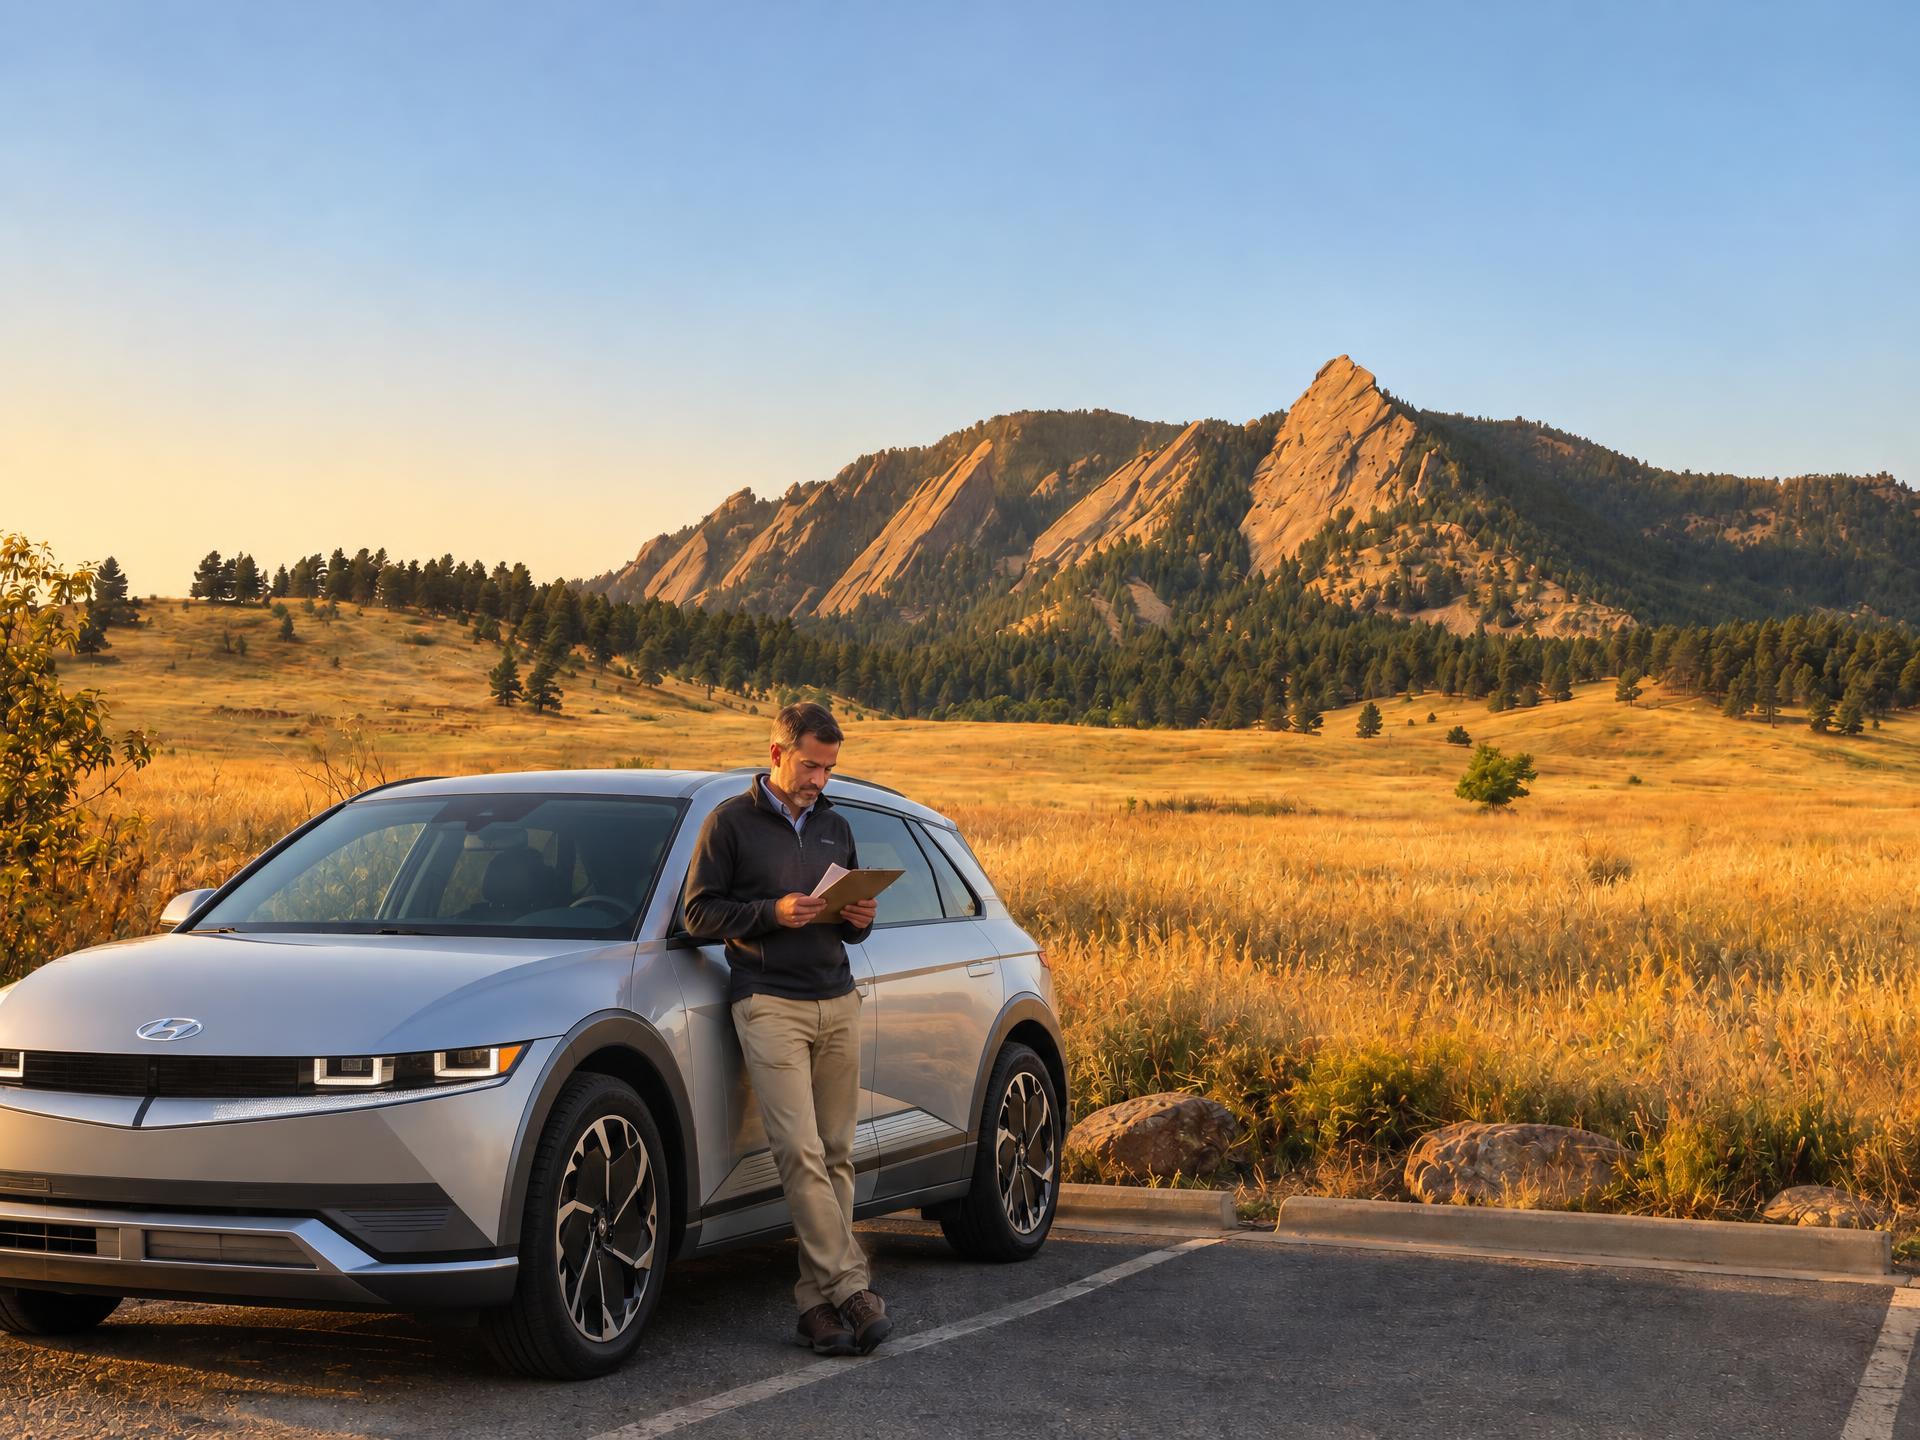
Leasing is usually not the cheapest way to drive a car over the long term. You're essentially paying for the steepest part of a vehicle's depreciation curve. Over the last few years, I have seen exceptions to this rule of thumb, notably electric vehicles before the expiration of the tax credit in September 2025. Now there are hundreds of thousands of drivers possibly not accustomed to leasing a car who are wondering what to do once it ends.
Know your residual and market values. The first step in determining an action plan for the end of your car lease is finding out the residual value in the contract. This is the price that you have the option to pay to purchase the vehicle at the end of the lease. This value should be available when you log into the leasing company website. It's also helpful to know the market value of the vehicle, which can be found using offers from local dealers, CarMax or Carvana. The market value may be close to the residual value, or it may be many thousands less or more. Start this process 60 to 90 days before the end of your lease, which gives you time to consider offers.
Return the car and walk away. This is the option that most people understand. At the end of the lease, you pay the disposition fee in the contract in addition to wear and tear and excess mileage charges. This option can be particularly compelling if the car is worth less than the residual value. Leasing companies often offer a pre-inspection so they can advise you of any issues that need to be addressed with your vehicle to avoid leasing company charges.
Keep the vehicle. This choice is also laid out in your lease contract. You can purchase the vehicle for the residual value by paying in cash, taking out a loan through the dealer, or finding other sources of financing. After exercising this option, you will own the car just like any other purchase transaction. As you might expect, this choice is more worthwhile when the residual value is below the market price. Essentially, you're buying a car below market value with the added benefit of a known service history.
Sell the car or capture its equity. This is another smart option to consider if the market value of the car is more than the residual value. If your leasing company allows third-party lease buyouts, you may be able to take your car to a dealer and use your "equity" toward the purchase of another vehicle. It's easier to understand this with an example. Imagine your vehicle can be purchased at the end of your lease for $28,000 including fees, but its market value is $32,000. If your leasing company permits it, you may be able to bring the leased car to the dealer that has the car that you want. You could then use this $4,000 in equity as a down payment toward the purchase of another car.
If your leasing company does not allow third-party buyouts, it may still be worthwhile to buy the car and trade it in for a vehicle at another dealer. Predictably, this move involves more hassle, the money needed to purchase your leased car, and perhaps additional taxes and fees.
Negotiate with the leasing agent or dealer. If the residual is above the market value of the car yet you still want to keep it, you can ask the leasing company or dealer whether they will negotiate. They may prefer to reduce the price you would pay to keep your car rather than have you turn it in, pay for the costs of reconditioning, and then selling it or sending it to auction. Also, some leasing companies offer the option to extend your lease for 6-12 months and continue the same payments. This can buy you some time while you figure out your next step.
If your lease is ending, you have more options than most people realize. Start the process early, know the market value and the residual value, and get an inspection before you decide. Don't base your decision only on the monthly payment and whether you like the car. With that knowledge in hand, you could save thousands as you weigh your next step.
David Gardner is a certified financial planner in Boulder County and is admitted to practice before the IRS. He can be reached at entreewealth.com. As financial planning is only possible after knowing the client, the column is not intended to be personal financial or tax advice. Data presented is believed to be accurate at the time of writing.
Subscribe to My Newsletter
Financial insights from David Gardner — delivered to your inbox. No paywall, no spam. Unsubscribe anytime.